
Yes, you have to make your own mistakes, but sometimes, what others do and did can help you avoid some of them or develop best practices faster. Also, solid knowledge can to that.
So I use my own experiences and publicly shown startup pitches as examples to showcase different aspects of business modelling, startup financials and investor negotiations. I hope it helps you!
For some more personal and often provoking insights from the startup scene or entertaining knowledge snippets, I'd like to refer you to my social media accounts.
Mostly Startup issues seen on the German "Shark Tank"
On what a flat revenue line tells investors - and what it doesn't
On when applause replaces the questions a pitch actually needs
On why “how many percent” isn’t always the right question to start with
On the thin line of positive self-marketing and losing investors' trust
On what it might costs or not to have values as a founder
On when it's to much with the KPIs during investor negotiations
On building a startup while travelling the whole world
On the importance of the RIGHT storytelling in a startup pitch
On the what an USP of an early-stage startup can consist of
Thursday, October 1, 2026
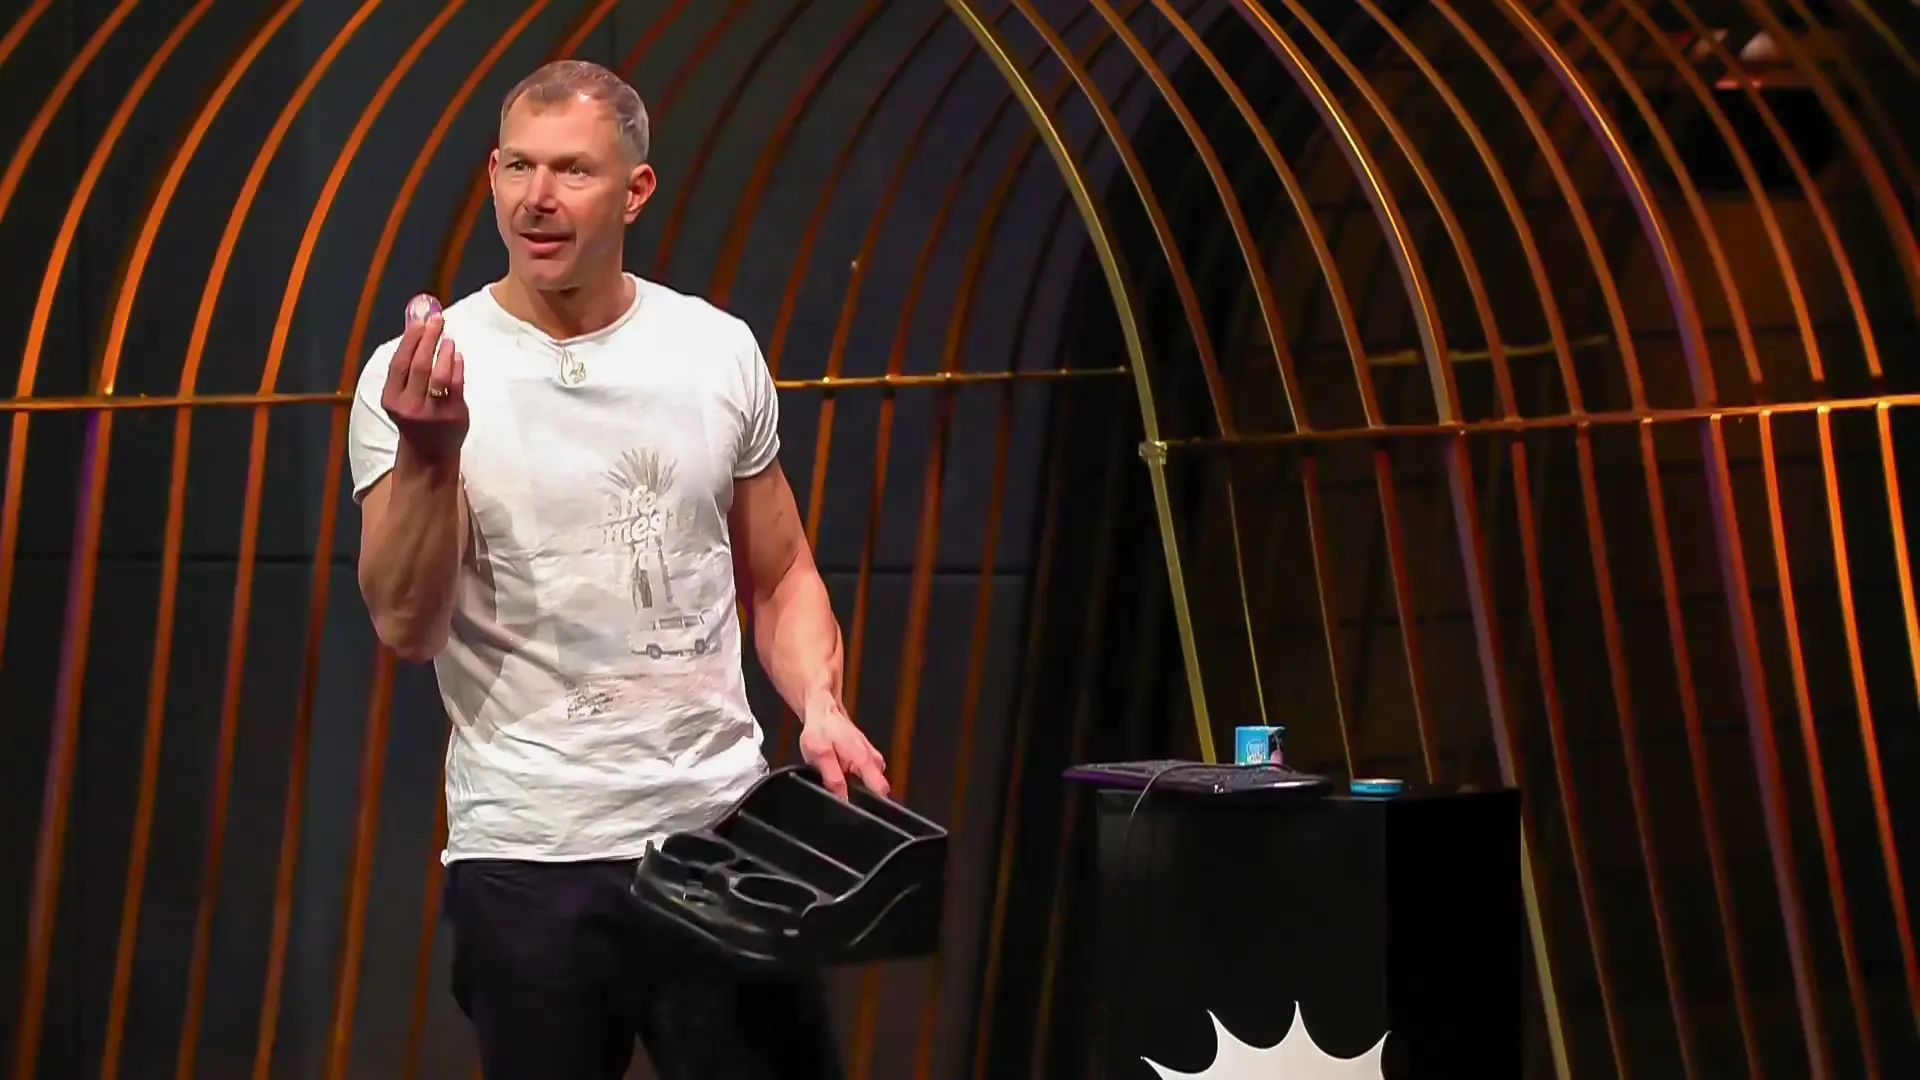
Susanne and Bernd Schmekel are a founding couple with two children, pitching No Crumbs GmbH. Their two products solve a problem many people know and few ever name: crumbs, sand and dust in handbags, jacket pockets, pencil cases and in crevices you never really get clean. But they've cracked it: their Sauberkugel is a sticky rubber ball inside a mesh cage that rolls through the bag with every movement, picking up whatever doesn't belong there. Once it's full, you click it open, rinse it with a drop of dish soap and put it back.
The Saubergeist is its flexible counterpart for tight spots like the center console of a car. Both are reusable, and the Sauberkugel is even patented.
The numbers, which the two wisely share right in the pitch, are impressive too: over 1.5 million units sold and €8 million in revenue over eight years. An 80 percent margin on both products and ten percent profit every year - after the founders' salaries. A genuinely profitable company.
They're listed in Germany's largest drugstore chain, and last year alone 120,000 Sauberkugeln went over the counter. They also already sell in other countries such as Japan, the US, Taiwan and Korea.
But the question that will shape the discussion comes up very early: during the pitch itself, the Lions ask about revenue and want to know, among other things, whether it has been growing or flat.
The answer is "constant", which seems to satisfy the Lions at first, because the pitch carries on. At the end, however, the couple justifies their need for capital by saying they can barely keep up with demand.
For investors, these are two statements that at first glance seem to contradict each other: if demand is greater than what can be delivered, you'd expect revenue to grow - at least up to the capacity limit. If it stays flat for years, that limit apparently lies somewhere else. Either the company has been sitting at that limit the whole time and should find ways to push it higher. Or something isn't right.
It's the question every investor has to ask at this point, and Frank Thelen in particular doesn't let go, soon asking the question that gets to the heart of it: why has no one been hired in eight years - why no salesperson who has already brought similar products onto the shelves?
That names the real crux of the matter, and it isn't about accusing the two of a mistake. It's about finding out whether the flat revenue is the symptom of a solvable bottleneck - simply a lack of capital for pre-production, for example, limited production capacity, or no sales power alongside day-to-day business. Or whether it's a sign that demand isn't enough for significantly larger scaling after all? Then it's a good, profitable business at exactly the size that suits it - but the model probably wouldn't have room for investors.
Which isn't a bad thing at all.
From the outside, that's hard to judge, and the minutes that were aired don't resolve it conclusively. There's evidence for both readings. An eight-year listing in the country's largest drugstore chain and inquiries from Asia and the US point to real demand. Revenue that has stayed flat for years suggests there's a limit somewhere. Which one it is, only numbers per channel would show: how fast does the product turn over on the shelf, how high are the reorders, and what happened to the inquiries that couldn't be served?
A little later, the founding couple explains quite concretely that they often can't accept large orders because they can't finance the pre-production. That isn't growth capital in the classic sense - it's working capital.
There are instruments for this that don't cost equity - inventory financing, factoring, an overdraft facility. In practice, though, they're often hard to get for small and young companies, because banks are still reluctant toward this segment. And a large pre-financing loan at your own risk is something many founders shy away from - understandably, because the risk then rests entirely with them. The fact that the Lions are known to often bring inventory pre-financing and purchasing structures alongside their investment makes an equity deal an understandable choice here.
In the end, there are three offers on the table, and the couple chooses Ralf Dümmel, who had offered €250,000 for 20%.
What remains is a case that resists a quick verdict, but is highly interesting. Two people built a profitable company over eight years while raising two small children, yet never managed to break through a certain threshold.
Now they have every chance to finally do it.
Photo (above): RTL
Tuesday, September 22, 2026
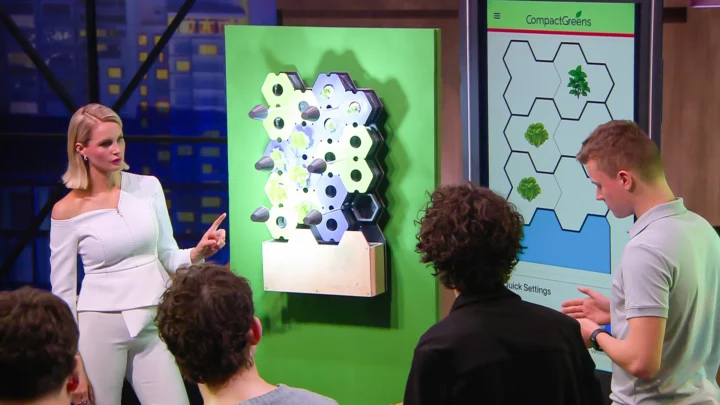
Five school friends, in the middle of their final exams, stand in Die Höhle der Löwen and present a product they have worked on for two years. By the end of the evening, they have two offers - both at exactly their conditions, without a single round of negotiation.
That is, first of all, a great story, and it should stand as one. The five boys have built something that works while dealing with exam stress, they explain it confidently and visibly enjoy doing it.
For Frank Thelen, they are in the top 5 percent of all founders when it comes to structure and answers. And from the jury: “This is what Germany needs.”
At least the last point is true: a country that produces young people with inventive spirit and drive can only be happy about it.
Their product is a modular plant wall for the kitchen, growing herbs and salads.
However, before the really big hymns of praise, it is worth taking a look at the market: indoor gardening is a category in which much bigger players have already failed. Miele acquired the Munich startup Agrilution in 2017 and discontinued its Plantcube in 2023 - a corporation with kitchen expertise, retail access and capital that still didn’t make it into the mass market. The business simply proved not economical enough.
Infarm, once the celebrated German flagship startup of the industry, left behind a mountain of debt of around 125 million euros - showing that the numbers didn’t work out in B2B either.
The pattern is always the same: high purchase price, thin follow-up business, seasonal attention instead of daily need - yet viewers don’t hear any of the Lions address this. Because the school friends’ system also has a high purchase price: customers must spend 250 to 350 euros, and the real profit is supposed to come from the follow-up business with the seedlings.
And that brings us to the numbers, especially to one really critical number: the five ask for an investment of 180,000 euros for 15 percent, which corresponds to a valuation of 1.2 million euros.
Here, for the first time, something like quiet criticism comes up - especially when the founders answer that the valuation is based on “team, revenue and IP”.
But as Frank Thelen immediately notes, revenue is zero.
Objectively, every professional investor would have to say that the team doesn’t really support the valuation either, compared with other founder teams. What would normally carry weight here is expertise, deep industry knowledge and relevant professional or founding experience.
None of this - naturally, if only because of their age - can these founders show. But an investor normally doesn’t decide based on “impressive for their age”. They decide based on “impressive compared with the entire market”.
The founders then argue with 170 “purchase inquiries” they are now beginning to deliver. But we don’t learn whether these are binding purchases, pre-orders with deposits, or just a kind of non-binding waiting list. How many actual customers can come out of this remains in the dark.
But even if all of them buy, that is around 51,000 euros in revenue. The cost comparison in the pitch is also worth recalculating: a seedling costs 1.30 euros, a comparable organic lettuce in the supermarket 2.20 euros, plus 17 cents for water and electricity. That makes 73 cents of savings per lettuce - with a device costing 250 to 350 euros. So you need 340 to 480 lettuces before the purchase pays for itself: customers here have to be true believers.
A lot falls victim to the editing cut, of course, and it is hard to imagine that the Lions really ignored all the obvious points of criticism - market, price point, customer benefit, missing validation and valuation - as completely as it appears in the aired version. What was shown, however, was an enthusiasm that needed no questions.
How different that can look was on display in the same season, just one week earlier. Anna from Frankfurt pitched CUPPED, made-to-measure bras based on self-measurement. Her numbers: 79 euros sales price at 14.60 euros purchase cost, over 1,100 customers, 30 percent of whom reordered within nine months, and 90,000 euros in revenue. Her return rate is 7 percent in a product category where 60 percent is normal. On top of that, she can already show an impressive CV at a young age. Here, numbers, founder and IP really did add up.
Two Lions offered her 200,000 euros for 30 percent - so they considered a valuation of just 666,666 euros appropriate.
Side by side, it looks like this: a profitable company with over a thousand customers and an exceptional reorder rate is valued at 666,666 euros. A company without a single euro of revenue gets 1.2 million - around 80 percent more.
Sure, with the five young founders the term “worthy of support” came up several times, which is certainly true. But is that really a reason not to negotiate a valuation that, in comparison, is so obviously inappropriate?
Economically, what happened here looks like plain nonsense. So emotional reasons obviously play a much bigger role. In Carsten Maschmeyer’s offer, with its reference to his own story, you can clearly hear that.
But at the latest when Dagmar Wöhrl introduces her offer with a reference to Waterdrop (“They were at exactly this stage when they came in here, like you were.”), you should pause: Waterdrop presented a hefty 670,000 euros in revenue back then - it had already reached a completely different level of maturity. The stages were not remotely comparable.
On the open market, too, we keep seeing funding rounds with steep valuations and little validation, and unfortunately a pattern emerges: strikingly often, young, white, male founders are behind them.
A study by BCG and MassChallenge put this into numbers a few years ago: startups with female founders received an average of 935,000 dollars in funding, those with all-male teams 2.12 million - and the women-founded startups still generated 78 cents of revenue per invested dollar, versus 31 cents for the male-founded ones. So it is apparently not about who delivers. It is about whose promise investors buy. And investors obviously trust very young, white, male founders the most, although the statistics speak a different language.
Whether the Lions fell for the same bias here, one can only speculate. In principle, it is wonderful that there are 19-year-olds who work on an idea for two years instead of just having it. But it is just as important not to praise them into the sky and let their egos explode before hard reality catches up with them.
Because no matter how much we enjoy youthful inventiveness: in the end, the market will decide whether the product gets a chance. And the market is merciless.
Applause is not a gift when it replaces questions. Encouragement is important - but it should be given to all young people equally.
If Dagmar Wöhrl’s deal really did go through, then everyone involved can only hope that she and her team now start asking the questions that were not to be seen that evening.
Photo (above): RTL / Bernd-Michael Maurer
Tuesday, September 15, 2026
Leonie from Berlin pitches Ivyclip - a hair claw. What at first sounds like the world’s most thoroughly solved problem quickly finds its punchline: the hair claw as we know it was invented in 1989 and has barely changed in over 35 years. And it pinches - so much that millions of women take it out the moment they lean back. When driving a car, it can even become dangerous. That’s about to change.
The unpleasant pressure when leaning back was also Leonie’s starting point, lying on the couch with her daughter. Her solution isn’t in the shape but in the material: a thermoplastic elastomer from medical technology. During her pitch she demonstrates vividly how much more flexible and durable her design is compared to a standard clip.
The Lions are captivated by the pitch, and it doesn’t take long before they steer the conversation to the numbers. And those numbers are the reason the evening unfolds the way it does.
Leonie explains that she mostly sells bundles of three clips through her website. A bundle costs €29.80, with unit production costs under €1. After VAT, cost of goods, shipping, and around €10 in marketing costs, roughly €5 in profit remains per bundle.
The Lions nod approvingly at that - but what follows genuinely excites them: Ivyclip has only been on the market for 2.5 months, generating €5,000 in revenue the first month, €14,000 in the second, and - in the last two weeks alone - a hefty €55,000.
So it’s almost a safe bet that revenue will cross the six-figure mark in month three.
The founder has done this by focusing on just three channels: influencer marketing as the main driver, her own organic videos (her first TikToks pulled 1.5 to 1.6 million views), and PR. She isn’t running any paid ads - no Meta ads yet - though she sees big potential there.
What follows is a bidding war - and four of the five offers are identical. Carsten Maschmeyer, Janna Ensthaler, Judith Williams, and Ralf Dümmel each offer exactly what the founder had in mind: €150,000 for 20%. None of them negotiate down.
Then comes Johannes Kliesch, new to the pack in this anniversary season and himself a successful online-commerce founder with Snocks. He offers €150,000 for 0%. In return, he wants €300,000 back - at €1 per hair clip sold. The company stays entirely in Leonie’s hands. His reasoning: giving away equity is the most expensive form of financing there is, and in this case it isn’t needed at all.
This instrument isn’t new to the startup world, though. Revenue-based financing is its own market outside the studio, especially for e-commerce brands with clean margins: a whole slate of providers finance marketing and inventory budgets this way, without taking equity. In the German shark tank, though, it’s still a new model - and a welcome one. For the first time in a long while, the question on the table wasn’t “how many percent” but “what kind of money” - and that changes the entire dynamic of the negotiation.
Because an offer that can’t be directly compared to the others quickly forces everyone else to explain themselves - and that’s exactly what happens here. Janna Ensthaler pushes back first, and her argument lands: the €1 per clip can go missing from exactly the budget Leonie needs to grow with; an equity investment, on the other hand, doesn’t have to be paid back - you can put the full amount into growth.
But as entertaining as the exchange is for the audience, the really interesting piece is this: both are right. They’re just talking about different strategies. And if you run the numbers, you can see how tight it gets. A bundle contains three clips, so €3 in repayment per bundle - against roughly €5 in profit. Until the €300,000 is repaid, about 60% of what you’d otherwise plow into the next growth phase is gone. After roughly 300,000 clips sold, it ends - the company would have hit around €3 million in revenue by then, and from that point on, she’d owe nothing. And she’d still hold all her equity.
So for whom might this kind of offer be the better one? For founders who mainly need starter financing, and whose need has a time limit. If you want to build online channels now and get a partner who has demonstrably done exactly that - Kliesch mentions a fifteen-person team and over €1 million in monthly creator budget - you’re buying a year of learning curve, not a decade of marriage. On top of that, the price is capped. €300,000 is the maximum this money can ever cost — 10% of a successful company is worth many times that over five years. The valuation debate disappears (a debate that, for a company ten weeks on the market, would rest on assumptions anyway), the cap table stays clean, and there are no additional clauses like consent rights or a liquidation preference that can make life difficult later on.
A really clean option with a manageable capital need and a healthy contribution margin at this early stage.
And for whom might the “classic” equity deal be better? For anyone who believes the journey will be longer, or who needs - or wants - longer-term support (or a different kind). That’s when Janna’s cash-flow argument bites. Even if further funding rounds are planned - for opening new distribution channels, say, or going international - you often want a partner who’ll accompany you long-term.
The most important point in this specific case, though, is a different one, and it has to do with Leonie’s own strategy: the founder wants to enter brick-and-mortar retail. She sees Ivyclip in drugstores, but she doesn’t come from retail herself and needs support there. That’s exactly where Carsten Maschmeyer builds his argument - he knows both owner families of the big drugstore chains in Germany, and he has Nippli in his portfolio: an investment that took this path and is still on dm’s shelves today. In the end, he raises the offer to €300,000 for 10%: twice the money, half the equity - i.e. four times the valuation originally asked.
The founder accepts, without consulting her husband - who himself stood in here nine years ago. “This is my company. I decide.”
With that, the valuation jumped from €750,000 to a full €3 million - for a company that has been selling for two and a half months.
Did the 0% offer “lose,” then? Quite the opposite: it set the negotiation in motion at all - four identical offers would have generated very little dynamic. Johannes Kliesch says it himself at the end, visibly with good sportsmanship: he’s sad about the missed deal, but he counts it as a small victory to have quadrupled Carsten’s offer. And he can for sure do that.
Not accepted doesn’t mean wrong. It just means: not the right fit for this founder’s preferred path. Leonie had a strategy - retail shelves rather than pure online growth - and she found the investor who matched that strategy. The offer outside the usual grid didn’t make the decision for her, but it turned it into a real one for the first time. And, in passing, it showed that before “how much equity do I give up,” there’s a different question that comes first: what kind of money fits what I’m actually trying to do?
Photo (above): RTL / Bernd-Michael Maurer
Thursday, September 5, 2025
The appearance of ‘Betta Salt’ seemed to have more potential to divide opinion than most. And not just in terms of divided opinions among the Lions, which seem to be quite common.Rather, some of the Lions themselves seemed torn in their decision-making. Frank Thelen, in particular, never tired of emphasising how enthusiastic he was about the basic concept, but at the same time he did not hold back with his criticism.In fact, the three-person founding team seemed to have developed the better salt: it is said to contain up to 50% less of the harmful sodium chloride and more healthy minerals, which also gives it a complex, less dominant taste.
And indeed, such a product seems sorely needed, as 99% of the world’s population probably consumes too much salt every day, far exceeding the 6g per day recommended by the WHO.
After the tasting, however, the lions quickly bring up a topic that seems to become the dominant component of this negotiation: a justification for the proposed 3.5 million post-money valuation is needed.Since the background of two of the three founding members as master’s students at WHU in the Entrepreneurship programme had previously received good feedback, they refer to this again in their answer. Unfortunately, they have to admit that this was not a good idea.When they mention the methods they learned, such as Berkus, VC or discounted cash flow, the lions burst out laughing.
One of the founders claims that he knew this would happen, but the question remains unanswered for viewers as to why he presented it this way.However, a quick web search reveals to anyone interested that the methods mentioned are actually among the best known and most widely used. So why this reaction?In fact, the latter, the discounted cash flow method, or DCF for short, has fallen out of favour, especially in the early stages of the start-up world. This is because it is based on assumptions about future cash flows, which can only be reasonably predicted once the start-up has been generating revenue for a while and can demonstrate a certain level of growth.
The VC method, on the other hand, is a good approach for looking at the valuation question from an investor’s perspective and adopting the appropriate mindset for negotiations – but it is also very imprecise and quite subjective, and is practically unusable as a sole approach.Finally, the Berkus method evaluates a start-up according to various factors such as idea, team or market potential. However, each factor is valued at up to €500,000, which can quickly lead to a very high overall valuation. This may be partly explained by the fact that developer Dave Berkus is an American investor, and European start-up valuations are often significantly lower.
However, this quickly leads to another important point: such methods and procedures were often developed in and for other markets and are therefore not so easily transferable. Not only does the geographical component play a major role here, but also the temporal one: trends change, hypes such as sustainability and AI come and go, and political events can also have a strong impact.
Unfortunately, many founders forget this when they apply the methods they learned at university or business school to their own start-up and are pleased with the rather high result.
This is probably what the Lions meant by ‘self-optimisation,’ which happens quickly when you use these methods without taking other factors – and thus reality – into account.But the founders seemed to take self-optimisation – or very optimistic self-presentation – a little too far for the Lions.
They claimed that there was so much demand for their product on the way to their actual planned B2B business model that they decided to also offer it B2C via an online shop – but when asked, they had to admit that they had only made €1,200 in sales so far.
Later, they claim to have ‘very good IP protection’ and assert that ‘no one will be able to copy this,’ even though they have not even filed a patent. However, when Frank Thelen reacts somewhat indignantly with ‘You can’t lie, that’s not okay!’, they respond with ‘I didn’t.’ And when asked, they correct themselves to say ‘we will have IP protection’. Even after rewinding several times, most viewers clearly understand this to mean ‘WE HAVE very good IP protection'.
Of course, there are more kinds of IP protection, but in this case, the discussion clearly refers to anything that could add to the company's value. And a brand protection or the company's registration clearly wouldn't do so.
Now, very few investors have a camera running, and in the heat of the moment, not everyone will presume to have understood every word correctly beyond doubt.But if you repeatedly gloss over things to your own advantage, you usually disqualify yourself completely as a start-up for serious investors.This is because you lose trust, which is the most valuable – and at the same time most sensitive – asset in the investment process.Once this trust is shaken, there is usually no way to salvage it.This is an even worse misstep than applying theoretical valuation methods without reflection.
Photo (above): RTL / Bernd-Michael Maurer
Friday, August 29, 2025
The 33-year-old Berliner was no stranger to entrepreneurship, having built up a company in his hometown called ‘Queere Haushaltshilfe’, which already employed 50 people – including heterosexuals.
Almost as an afterthought, he then developed anuux – a dietary supplement designed to ensure optimal digestion and thus a clean rectum. Ideal for lovemaking ‘at the back door’ – and, of course, for heterosexuals as well.
It quickly became apparent that the lions were not only very taken with his personality, but also found his product quite interesting.Anuux has been sold online, in pharmacies and in a shop in Berlin for three years now, and Marius also spends a lot of time travelling to trade fairs.
However, marketing the capsules containing psyllium husks, chia seeds and flaxseed husks to the target group does not only have advantages: online, overly direct communication of the intimate benefits quickly risks a shadow ban, while offline, some potential sales outlets are still wary of the product – even in 2025.
This does not seem to be the case with the Lions: after all, Janna Ensthaler had already explained the functionality of the enema ball included in the set to her fellow Lions before the pitch began.
So, in typical Lion fashion, they quickly get down to the numbers: the recommended amount of capsules costs customers around 1€ per day, and annual sales of around 60,000€ have already been generated.
The mood in the den seems to be very good, thanks in no small part to the founder’s very clear answers, who at the same time manages to communicate his topic with relaxed openness.
Frank Thelen quickly dismisses the possibility of a deal, as it is not a product for him. However, the other Lions delve deeper, asking about the company setupand background, which is often a sure sign of stronger interest.Nevertheless, retail lion Ralf Dümmel soon leaves the field to the ladies, as he considers the product – especially with its very specific target group orientation – to require too much explanation for omnichannel distribution.
And it is precisely sales and marketing, which pose a particular challenge for such a product, that become the sticking point: when asked by Dagmar Wöhrl what exactly the founder wants from a Lion, Marius mentions, among other things, the shadow ban on social media and that he needs more expertise in online marketing at his side in order to better address this challenge.
This is another reason why Judith Williams ultimately utters the dreaded words ‘I’m out’: she sees the inability to communicate freely in marketing as one of the problems that put her off the start-up.
However, when Marius emphasises that this applies primarily to Instagram, but not necessarily to all platforms, Janna Ensthaler throws another marketing opportunity into the ring with X, which Marius immediately rejects because he does not want to support the platform due to his political stance.
Ultimately, however, this seems to be the reason for the lioness’s decision to pull out, as she praises the founder’s pitch, presentation and product, but emphasises that she wants openness from her founders and does not want to work together on this basis.
This is where many people will have asked themselves the question: can a start-up looking for investment really afford to take such a stance? Isn’t it generally critical to completely close yourself off to a particular marketing approach?From the investor’s point of view, this stance is certainly understandable. After all, you can’t really criticise an investor for their business model. And that model is usually aimed at achieving the best possible growth for the companies in their portfolio.
But as always, there is more than one side to such an issue: from a purely sales perspective, it is of course critical to completely exclude a potential channel.On the other hand, X has been in the headlines in the past for alleged homophobic tendencies. Although Elon Musk took action against this, such things can still lead to a corresponding image, regardless of their truthfulness.
But as always, there are two sides to this issue: from a purely sales perspective, it is obviously critical to completely rule out a potential channel.On the other hand, X has made headlines in the past for alleged homophobic tendencies. Although Elon Musk took action against this, such incidents – regardless of their veracity – can still damage a company’s image.
In the medium to long term, any company that advertises on such a platform must consider the impact on its image and branding among its target group. In the short term, open differentiation could block the path to an additional marketing channel, but in the longer term it could make a decisive contribution to the company’s brand building – simply because it is perceived positively and as authentic by the target group.
Ultimately, it is not only personal conviction that must be weighed against operational measures, but also the overarching brand strategy. This is a prime example of a difficult decision for founders.
Unfortunately, there was no deal for annux in the end, but there was an exciting pitch with a likeable founder who stood by his values.
We can only hope that television will make up for the lost channel and that his efforts to build an authentic brand will eventually be rewarded.
Photo (above): RTL / Bernd-Michael Maurer
Thursday, June 6, 2025
Most investors cannot emphasise enough how important key figures are for their investment decision.
Unfortunately, many start-ups simply don’t provide them, preferring to propagate storytelling until they drop in pitch training sessions. But smart founders can use this to their advantage: If you have your figures under control and a solid idea of what the most important key figures are for your own business and how they will develop, you will stand out positively.
But if you rely solely on this effect, or even use it to cover up weaknesses or justify an abstruse valuation, knowledgeable investors will recognise this and even judge it negatively.This was also the experience of the founders of TukToro in the latest episode of ‘Die Höhle der Löwen’.
Their start-up, which had developed a maths learning toy for children, was actually very well received by the lions. However, its price of €79, production costs of €25 and, above all, the proposed valuation of a whopping €5 million did not arouse any enthusiasm among the lions.Of course, the familiar valuation discussion soon began. The founders initially cited their sales pipeline, which was said to be worth an impressive 1.3 million euros. However, the lions Ralf Dümmel and Carsten Maschmeyer drilled this down until there was not much left. When questioned more closely, the founders had to admit that the €1.3 million in sales were not signed orders, but rather declarations of intent – legally non-binding letters of intent that did not have to materialise as actual sales, or perhaps not at all. The startup had only actually realised 56,000 euros so far, but the paraphrase ‘in the account’ again allowed for intentional or unintentional errors, which the audience did not find out whether they had been clarified.
However, Carsten Maschmeyer’s reaction was very vivid: he clearly pointed out that Ralf Dümmel’s enquiries were primarily based on the very high valuation, which he very much doubted due to the rather uncertain sales situation.
But the founder countered more than confidently that he believes he can justify the valuation ‘in any case’ and argued that TukToro could be sold or licensed to learning institutes as a software-as-a-service model – he then found the multiple of around 4 on the – not yet certain turnover, mind you – completely justified by this other business model.
It is true that such business models can achieve higher valuations, because of course recurring revenue is a more attractive metric than one-off sales. However, if you are relying on this, you should have already implemented at least parts of the business model and be able to show that you can win customers with it.But justifying a multiple on potential sales with a potential business model is clearly beyond self-confidence.
Carsten Maschmeyer promptly criticised this, because for him the business model of €79 one-off sales was still the measure.But the founders weren’t finished yet: they are reportedly confident that they can increase the customer lifetime value from €79 to €250 with additional figures, e.g. through licences with superhero figures.
And indeed, such arguments with these key figures are very popular with investors, as they show that the founder has a plan for how to continue growing.However, tripling the important CLV figure should not be presented as something that can be achieved ‘just like that’, as this will make any investor who is even halfway competent suspicious.
For Carsten Maschmeyer, the founders’ approach to the valuation argument was “completely weird and audacious”, but they still didn’t give up.They challenged the lions, saying that they were exactly the founders who had the big vision that was so often sought after, and that they needed a lot of money to realise it. This was followed by flowery sentences such as ‘before we’re on the market, people are already running into us’, or, in relation to an upcoming study, ‘for the first time in the history of mankind, we can quantify education’. In both cases, at least the viewers – but also the lions, judging by their reaction – are completely deprived of any explanation.Carsten Maschmeyer contradicted these seemingly abstruse claims with increasing vehemence, and the TV investors dropped out one after the other. Yet the founders were so sure of getting a deal – on a scale of 1 to 10, one of them gave 11, the other 12-13 in the pre-interview.
In addition to the KPIs, this is another example of dealing with numbers that even the best learning app cannot explain.
Afterwards, the lions understandably surmised that the founders were probably never really interested in a deal.
Whether this is the case will probably remain pure speculation. However, it cannot be ruled out that they will get through to other investors with exactly this type of ‘argumentation’ with a completely abstruse valuation – because many German investors in particular are always happy to show that they prefer to support precisely this type of founder. Unfortunately, some of them need some extra tuition themselves when it comes to company key figures.
Photo (above): RTL / Bernd-Michael Maurer
Friday, June 6, 2025
The stage design of the start-up ‘Moncourage’ already made it clear that it is all about travelling, and founder Eva starts her pitch by explaining that she has just arrived from Sri Lanka. And so she also explains that she herself had the problem of having too much ballast on her many journeys due to all the personal care containers, and also the danger of leakage always travelling with her.
That’s why she spent over a year searching the world for the best ingredients to develop solid all-in-one products with the perfect consistency from Alaska to the tropics. The result was a sun protection stick and a skincare stick that replaces lip balm, face cream, hand cream, body lotion, after-sun lotion and even make-up remover. The ingredients come from Equador, Mexico, the Philippines, Morocco and Brandenburg – the founder knows every single producer by name and has been shown the entire production process in detail.
This impressed the lions, as did her background as an expert in medicinal plants, aromatherapy and natural cosmetics.
The product is then also very well received by the lions, as is its margin and the turnover of almost €100,000 in one year to date.But just as the viewers begin to think that the lions are about to make their first offer, the mood threatens to change.
First, Nils Glagau drops out because he cannot combine brand building with the idea of encouraging women to live their lives with skin care.
Carsten Maschmeyer makes a similar comment, although he initially speaks very favourably of the founder’s courage and her product.But then the conversation quickly turns back to travelling and the lions ask several times whether founder Eva really has no fixed abode. She patiently explains the various facets of her life of constant travelling: that she has also searched for the best raw materials for her product, but that she has practically always felt at home anywhere in the world and has therefore structured her company from the outset in such a way that she does not necessarily always have to be in one place. But of course she can always go wherever she is needed.But that’s not enough for Tillmann Schulz. He explains that, in his opinion, this is not possible in the start-up phase because you have to be available more quickly and therefore cannot be on the road. He firmly believes that it is essential to monitor production yourself, take samples and check other things.
Did he consider in all these remarks that the founder sources her raw materials from suppliers around the world and that perhaps it is precisely her constant travelling that allows her to carry out the required activities?
But Judith Williams also drops out for similar reasons: for her, a permanently travelling founder seems too complicated, she has probably had bad experiences with the combination across different time zones.Of course, it is difficult to argue against the bad experiences of investors, as it is often not really possible to do anything about them.
But how rational is the argument?If you take a look at the constantly growing and, above all, now highly professionalised scene of entrepreneurs among the ‘digital nomads’, it quickly becomes clear that long-term travel does not necessarily have to have a bad impact on a start-up. Many of these travelling founders are highly organised, used to adapting to specific time zones all over the world and often their partners, investors and customers don’t even notice where they are.
Many have a high degree of discipline – no wonder, after all, they often have to work in the most beautiful places while watching the holidaymakers idle away their time. There is a lively exchange among them – especially with regard to best practices or the most efficient technical solutions for every situation.
In view of the reality of these entrepreneurs, the blanket platitude ‘You can’t travel in the start-up phase’ seems more like a remnant from a very analogue world.Ultimately, it is also Ralf Dümmel who gives this discussion the space it deserves – and pushes it to the margins. After all, he also prefers personal contact, but he knows that times have changed and that there are now the technical means to always be reachable anywhere else in the world.He is now focussing on the product and the founder again, as both have completely won him over. So he finally makes an offer: he now wants 22% instead of the originally planned 15% for the requested €150,000 – but the founder happily accepts.
As a small speciality, she was advised by Judith Williams, which made Ralf Dümmel tremble briefly – but in the end everyone involved seemed very happy with the result.
A nice ending that is just the beginning. And once again a demonstration that investors are only human: some may miss opportunities due to bad experiences, some hold on to outdated beliefs – and some have the courage to arrive in the modern world to create something even greater.
We can only hope that this courage will be rewarded on all sides in this case.
Photo (above): RTL / Bernd-Michael Maurer
Friday, May 30, 2025
Founders Raphael and Martin were extremely confident that they would be able to present their lunchbox to the lions and started their pitch with an important topic: the increasing amount of waste in nature, which every mindful outdoor sports enthusiast is sure to have noticed at some point.
They were also bothered by this and were inspired to launch a movement that has set itself the goal of cleaning up – and is now doing so across Germany and beyond during their so-called ‘clean-up days’.
These are meetings of volunteers who, armed with tongs and bin bags, go out into the countryside and remove rubbish from popular places. Volunteers can use an app to see where the next event is taking place and everything is organised online.
Over 50,000 people have now taken part, the movement has over 30,000 active users and estimates that it has already collected over 20 tonnes of waste.
However, this is not the ‘solution’ to the initial problem of waste in nature that the two founders are ultimately pitching. Their actual – and truly commercial – product is a different one.
The pitch actually revolves around the lunchbox they developed, which not only contains a wooden chopping board and a knife, but can also be attached to the leg with a strap to create a mini table.
There is also a barbecue grid with a gas connection which, together with a commercially available cartridge, turns the lunchbox into a barbecue in seconds.
The product is perceived as imaginative and of high quality, but very quickly Lion Nils Glagau seems to turn the conversation to something that has probably caught the attention of all the lions: how does this product prevent littering in nature?
The two founders argue from several sides, mentioning the basis of the clean-up community, in which they have successfully sold the box around 10,000 times without a marketing budget and thus generated over one million sales. They also argue that this community marketing and strong connection with the clean-up movement makes their customers even more aware of the problem of waste avoidance, and that a lunchbox – especially in combination with a knife and chopping board – helps to prevent people from going out with unsustainably packaged food in the first place.
But the TV investors seem to have realised that there is no direct link here and are dropping out one by one. So how could this happen despite good figures and the otherwise popular social aspect of the business model?
A major problem with Patron’s pitch could be that, although it appears to follow the usual narrative structure of ‘problem – solution’, it doesn’t actually do so. This is because investors are used to being told the problem of a target group before the solution is presented.
This has established itself in the start-up world for a reason: not only is a pitch easier to understand, but it can also make the audience curious about the actual product and secure their attention. And if the two fit together really well and the pitch convincingly presents the so-called ‘problem-solution fit’, you hardly have to explain the raison d’être and often also the USPs – i.e. the unique selling points – separately.
But on the other hand, professional investors are also trained to think through this problem-solution fit in detail – and unfortunately, in the case of Patron, it became apparent that something didn’t really fit here.
Even though the clean-up events are part of the lunchbox’s origin story, the strong community is more a part of the Patron brand or supports it and enabled the great early sales figures despite the rather high price of up to €109 per box.
If we had wanted a clear problem-solution structure, it would probably have made more sense to describe the problem of the conscious and sustainably orientated outdoor sports enthusiast who cannot find a high-quality lunchbox that meets all their requirements.
But no matter how tried and tested the familiar structure is, not every start-up pitch has to follow it. If it’s done well, breaking with familiar patterns can even attract more attention.
An alternative for the pitch structure might have been to make it clearer that you first tell the story of the company’s origins and then emphasise the very good sales figures. This would have given investors the chance to concentrate on what they are pushing for the most: Making money.
Because good storytelling may distract for a while, but it can never really eradicate the numbers part. However, unclear storytelling simply causes confusion in the worst case and, as in this case, sometimes unfortunately means that even good figures don’t really come into their own.
Photo (above): RTL / Bernd-Michael Maurer
Friday, May 9, 2025
On Monday, the mother-daughter team Mirjam and Ellen presented a portioned porridge with collagen to the lions. So you can do something for beautiful skin while eating breakfast.
However, even the relatively small deal of €50,000 for 20% did not result in cries of enthusiasm from the lions, as they quickly got hung up on two points:Firstly, they considered the product to be quite expensive, or at least too expensive to reach a wider audience. Although the ratio of production costs to sales price per bag of around €1.10 to €2.99 was basically okay for such a young start-up, this was only because the sales price seemed quite high. This did not seem promising enough for the investors, especially for retailers.
On the other hand, there was a lot of discussion about the USP, and the final cut at least suggested that the founders were unable to provide a truly satisfactory answer. Although they tried to emphasise the special quality of their collage, this alone was too easy for the lions to copy. The combination with a porridge in a ready-made sachet for quick breakfast preparation didn’t really go down well either.
This discussion could easily make founders doubt whether their own USP is strong enough. Because if you follow these arguments, it would be very difficult for the vast majority of food start-ups to formulate a USP that is strong enough. After all, large corporations could copy their recipes or blends quite quickly.But why do start-ups always manage to win the hearts of consumers after all? Is the fear of copying not so justified after all, or how can the success of various products on the food shelf be explained, for which the large corporations have not yet been able to provide any real competition?
If you take a closer look, these products are usually not exactly cheap, which is certainly due to the smaller quantities and therefore higher production costs, especially at the beginning. On the other hand, it is also simply due to the fact that start-ups in particular often operate in a market segment that fulfils consumer demand for higher quality – and in the food sector often healthier – alternatives. However, these customer groups are usually aware that quality usually comes at a higher price and they are often both more affluent and more willing to pay.However, large corporations often have an image problem in these market segments: customers literally don’t buy their high quality and, above all, certain sustainability aspects – and prefer to trust small start-ups that their promises are not marketing lies. In fact, corporations have often had problems with acquired brands whose image did not survive the acquisition.
Of course, a USP is and remains one of the most important criteria for investors. Simply because a strong USP means poorer copyability and better marketing opportunities. Of course, this reduces the risk of a total failure due to suddenly blossoming competition that simply has better distribution, for example.
But shouldn’t a good early-stage investor also recognise a USP that may simply not have been communicated so well? Or even better: help a good team with potential in the product to build it?
If you listened closely to Corridge’s pitch, you may have picked up on a few key points that initially seem like a kind of ‘standard for food start-ups’. At least for those who want to establish themselves in the higher-quality market segment mentioned: no additives, no additional flavourings, no added sugar.
But are they really all so obvious? Anyone who has ever looked for a low-sugar and preferably high-protein porridge or muesli knows what a drama it can be. Less than 10g of sugar per 100g seems like a sheer impossibility in a normal supermarket.
But the Corridge Banana impresses with just 5g of sugar and over 23g of protein. For many nutrition-conscious cereal breakfast fans, this seems almost like a blessing and is certainly not a matter of course on the current market – and if it is available at all, it is usually not exactly cheap.
But lioness Janna Ensthaler had an even more far-reaching idea: how about taking the collagen muesli as a starting point and setting her sights on the grand vision of developing into a provider of porridge with added nutritional supplements? She saw more potential to build up a corresponding USP for this, but she also wanted 10% more shares in the food start-up.
The founders agreed, and the new products appear to be in development. If you now search for ‘porridge with collagen’, Corridge actually ranks at No. 1 in the unpaid search results on Google.
So it seems that the courageous investor is now also being rewarded with an original USP that is stronger than initially assumed.
Photo (above): RTL / Bernd-Michael Maurer


No fluff, just valuable content.

